Point-to-Point and Gaining Ground: How Santiago-US Express Corridors Are Challenging the Hub-and-Spoke Establishment
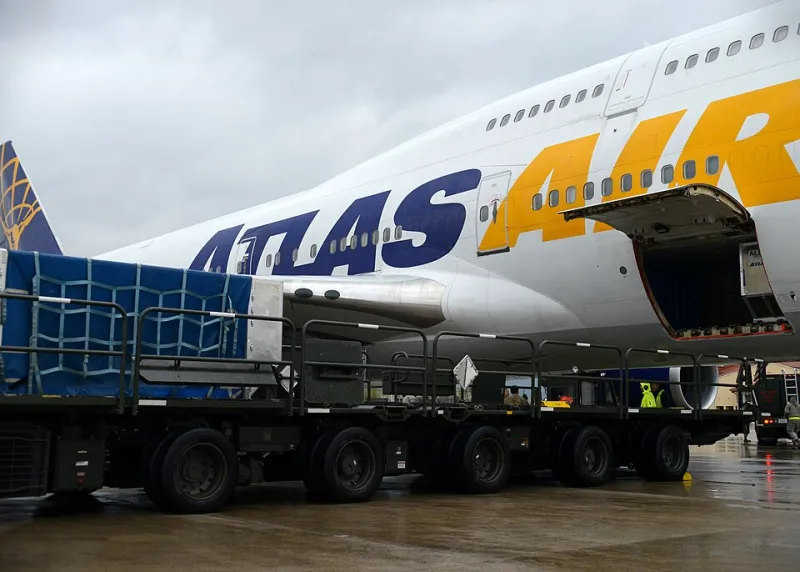
Photo: U.S. Air Force photo by Staff Sgt. Rebeccah Woodrow, Public domain, via Wikimedia Commons
The Architecture of the Old Order
Hub-and-spoke logistics is not merely a business model — it is an organizing philosophy, one that has shaped how goods move across continents for the better part of a century. The logic is straightforward: concentrate freight at major nodes, achieve density, then radiate outward to secondary and tertiary destinations. For the mega-carriers and global freight networks that built their empires on this model, it has been enormously profitable.
It has also, increasingly, been a source of friction for the shippers it is supposed to serve.
Every hub introduces delay. Every spoke adds a handling event. And every handling event is an opportunity for error, damage, or cost accumulation. In the current freight environment — where shippers have access to real-time tracking, where e-commerce has compressed delivery expectations, and where supply chain disruption has made redundancy a strategic priority — the inefficiencies embedded in hub-and-spoke architecture are harder to ignore than they once were.
Into this environment, direct express corridors have entered with a different proposition: fewer stops, faster movement, and a service model built around accountability rather than aggregation.
What Point-to-Point Actually Means
The term "point-to-point" is sometimes used loosely in logistics marketing, so precision matters here. A genuine point-to-point express service moves freight from origin to destination without intermediate consolidation at a third hub. The shipment does not stop in Miami to be sorted before continuing to Chicago. It does not transit through a European gateway on its way from South America to the US East Coast. It moves directly, on a defined schedule, with a single accountable carrier.
For Santiago-to-US corridors specifically, this architecture has become increasingly viable as air cargo capacity between Chile and major US gateways has grown. Routes connecting Santiago directly to Miami, Houston, and Los Angeles now operate with sufficient frequency to support reliable express schedules. The transit times achievable on these routes — particularly for air freight — are competitive with, and in some cases superior to, what shippers can obtain by routing through traditional intermediary hubs.
The implications are significant. A shipper moving high-priority cargo from Santiago no longer needs to accept the dwell time and handling risk associated with consolidation in a third country. The freight moves, it clears US customs at the destination gateway, and it reaches the consignee. The process is simpler, and simplicity has operational value that does not always appear on a rate sheet.
The Competitive Pressure on Established Carriers
The major international freight networks are not oblivious to this development. They have watched point-to-point services gain market share in other trade lanes and they understand the structural threat. A shipper who discovers that a direct corridor delivers faster and more predictably than a hub-routed alternative does not easily return to the old model.
The response from established carriers has taken several forms. Some have invested in expanding their own direct service offerings on high-demand corridors, attempting to compete on speed rather than ceding the market to more nimble operators. Others have leaned into their scale advantages — broader network reach, more extensive last-mile capabilities, deeper customs brokerage infrastructure — to argue that hub-and-spoke remains the superior choice for complex, multi-destination shipments.
Those arguments have merit in certain contexts. A company moving freight to thirty different US zip codes in a single shipment cycle is not the natural customer for a point-to-point express service. But a company moving time-sensitive, high-value cargo to a single distribution center or fulfillment hub — and that describes a substantial portion of the commercial freight market — may find that the established carriers' network breadth is less relevant than they suggest.
Technology as the Differentiator
One of the underappreciated dimensions of this competitive dynamic is the role of technology in reshaping shipper expectations. Real-time shipment visibility, predictive delay notification, digital customs documentation, and API-connected freight booking have moved from differentiators to baseline requirements in a remarkably short period of time. Shippers who once accepted opacity as an inherent feature of international freight now expect to know where their cargo is at every stage of its journey.
Point-to-point express services, by virtue of their simpler operational architecture, are often better positioned to deliver on these expectations. Fewer handoffs mean fewer gaps in the tracking chain. A shipment moving directly from Santiago to Miami is easier to monitor continuously than one transiting through two intermediate hubs. And when a problem arises — a customs hold, a mechanical delay, a documentation issue — the accountability structure of a direct service is clearer, which typically means faster resolution.
The technology investments being made by express corridor operators in the Santiago-US market reflect this reality. Carriers competing on this lane are building visibility infrastructure, automated exception management systems, and customer-facing tools that match or exceed what the legacy networks offer. The technology gap that once favored large hub-and-spoke operators is narrowing.
Market Consolidation and What It Signals
The growth of direct express corridors has not gone unnoticed by investors, and the M&A activity in this segment of the Latin American logistics market reflects genuine conviction about where the industry is heading. Established regional carriers have acquired or partnered with express-focused operators. Technology platforms have entered the space as intermediaries, aggregating capacity across direct service providers and offering shippers a single interface for booking and management.
This consolidation is a signal worth reading carefully. When capital concentrates in a market segment, it typically means that the underlying economics are compelling and that the growth trajectory is credible. The Santiago-US express corridor is attracting that kind of attention.
For US shippers, the practical implication is that the competitive options available on this lane will continue to expand over the near term. More carriers, more technology platforms, and more service configurations will enter the market. That is generally good news for buyers, who will have more leverage and more choice. It also means that the analytical work of evaluating providers — comparing transit times, reliability records, visibility capabilities, and total cost — becomes more important, not less.
Choosing in a More Competitive Market
The disruption of hub-and-spoke dominance by direct express corridors does not mean that the old model is finished. It means that shippers now have a genuine choice where previously they had a default. Making that choice well requires clarity about what matters most for a given freight profile: Is speed the primary variable? Is cost? Is it reliability, defined as consistency of transit time rather than raw velocity? Is it the ability to handle exceptions gracefully when they occur?
Different shippers will answer those questions differently, and the right service model will vary accordingly. What is no longer defensible is choosing a logistics architecture out of habit rather than analysis. The Santiago-US express corridor has made that analysis worth conducting. The results, for many shippers, are likely to be instructive.